
Zero-Based Budgeting for Households Juggling Debt and Savings Goals

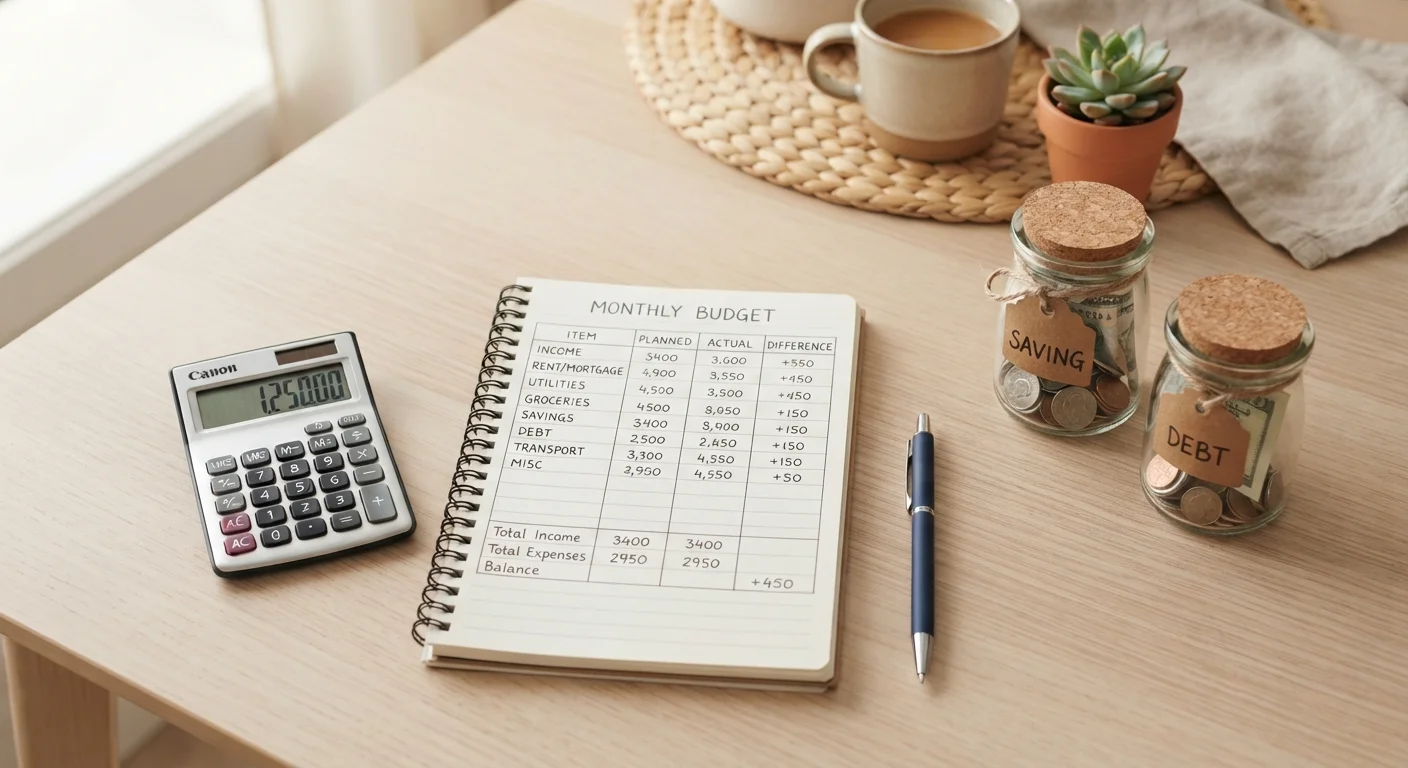
Zero-based budgeting assigns every pound a job. Learn how to apply this method when your income must stretch across debt repayments and future savings simultaneously.
Key takeaways
- Zero-based budgeting assigns every dollar of income to a category so nothing is left unaccounted for.
- You can carry debt and save at the same time using deliberate category ordering.
- Minimum debt payments come before discretionary spending, but small savings contributions can run in parallel.
- The budget resets each month, letting you adapt allocations as income or expenses shift.
- A licensed financial professional can help tailor a debt-and-savings strategy to your specific situation.
What zero-based budgeting actually means
Zero-based budgeting (ZBB) is a method where you take your total monthly income and assign every dollar to a named category until you reach zero. That does not mean spending everything. It means every dollar has a written job, whether that job is paying rent, making a debt payment, or sitting in a savings account.
The method differs from looser tracking approaches because it is forward-looking. You build the plan before the month starts, not after the money has already moved. If you are working across both debt repayment and savings goals at the same time, that structure matters because it forces you to make explicit trade-offs rather than hoping the math works out at the end of the month.
For a grounding in how to map your spending before building any budget, see separating fixed from flexible expenses, which covers how to categorize costs so you know what is negotiable and what is not.
How to set up the budget when debt and savings compete
The most common friction point is feeling like debt repayment and savings are competing for the same dollars. In a zero-based framework, you resolve that tension by sequencing categories deliberately rather than splitting whatever is left over.
Write down your actual take-home income
Start with the money that lands in your account after taxes and any automatic deductions. If your income varies month to month, use the lowest amount you received in the past three months as your baseline. Building a budget on a number you might not hit creates a shortfall before you begin.
List every fixed expense first
Fixed expenses are costs that do not change month to month: rent or mortgage, utility minimums, insurance premiums, and minimum debt payments. Write out each one with its exact amount. These go into the budget first because they are not optional and the amounts are predictable.
Assign a savings category before flexible spending
After fixed expenses and debt minimums, the next line in your budget should be savings, even if the amount is small. Placing savings ahead of discretionary spending means it gets funded rather than receiving whatever survives the month. A modest but consistent monthly contribution to an emergency fund or a specific goal does more over time than occasional large deposits when money happens to be left over.
Allocate flexible spending categories
Groceries, transportation, clothing, dining out, subscriptions, and personal spending are flexible: the amounts can move depending on what the month requires. Assign a specific dollar amount to each category. Be realistic rather than optimistic. If you consistently spend $400 on groceries, budgeting $250 will not hold.
Apply any remaining dollars to extra debt payment or savings
Once every category has a number, total them up and subtract from your income. If the result is above zero, you have unassigned dollars. Those go to either accelerated debt repayment or an additional savings contribution, depending on your current priorities. Assign them explicitly to one or the other. Do not leave them in a general buffer where they will dissolve into untracked spending.
Review and rebuild the budget at the end of each month
ZBB resets monthly. At month-end, compare what you budgeted against what actually happened. Categories that ran over need either more funding next month or a behavior change. Categories that consistently ran under can have their allocation reduced so those dollars go somewhere more useful. This review is the mechanism that makes the method improve over time.
If you and a partner are building this together, the allocation conversations can get complicated quickly. Budgeting as a couple covers how to align on priorities without turning every budget meeting into a negotiation.
This article is general financial information and education, not personalized financial, investment, tax, or legal advice. For guidance specific to your circumstances, consult a licensed financial professional.
Common mistakes that derail the first few months
Most households that try ZBB and abandon it do so because of a few predictable problems, not because the method is wrong for them.
- Setting categories too broadly. A single "miscellaneous" bucket defeats the purpose because it becomes a catch-all that hides spending patterns.
- Forgetting irregular expenses. Annual insurance premiums, car registration, and seasonal costs do not appear every month, but they will arrive. Divide the annual total by 12 and fund that category monthly.
- Treating the first month as the final version. Your first zero-based budget will almost certainly be wrong in places. Treat it as a draft and adjust at the month-end review.
- Stopping debt minimums to boost savings faster. Skipping or underpaying minimum debt payments can trigger late fees and credit score damage. Minimums are not optional line items.
Before accelerating debt payoff beyond minimums, it is worth running through a short checklist to confirm you have buffers and basics in place. A pre-debt-payoff checklist walks through exactly that.
Build the review into your calendar
Schedule a 20-minute budget review on the last day of each month. Treat it as a fixed appointment. Households that skip the monthly review tend to repeat the same allocation errors and lose the main benefit of the zero-based approach.
The content on this site is for informational purposes only and is not a substitute for professional advice. Always consult a qualified professional for guidance specific to your situation.