
How Couples Navigate Financial Disagreements Constructively
Money is one of the most common sources of tension in relationships. Explore communication strategies that help partners address financial differences with less conflict.
Key takeaways
- Money disagreements in relationships are normal and do not signal incompatibility.
- Timing and tone matter as much as the content of a financial conversation.
- Couples who schedule regular money check-ins report fewer surprise conflicts.
- Separating spending values from personal worth reduces defensiveness in discussions.
- A shared financial framework gives partners a neutral starting point for decisions.
Why money disagreements feel personal
Few topics carry as much emotional weight in a relationship as money. How a person spends, saves, or thinks about debt is shaped by family history, past hardship, and deeply held beliefs about what a good life looks like. When two people with different financial backgrounds share a life, those differences collide, sometimes loudly.
The conflict is rarely about the specific purchase or account balance in front of them. It is usually about whose values get to set the tone. That is why a disagreement over a grocery bill can spiral into something that feels much bigger. Understanding this is the first step toward talking about money without it becoming a referendum on one person's character.
For a broader look at what separates productive disagreements from harmful ones, see the anatomy of healthy conflict.
Practical approaches that reduce friction
The strategies below are not about eliminating disagreement. They are about giving both partners the conditions they need to stay in the conversation rather than shut down or escalate. Stonewalling, which is the act of withdrawing entirely during conflict, is one of the most damaging patterns in couples communication. If that tendency shows up in your financial conversations, understanding why stonewalling happens can help you interrupt it before it takes hold.
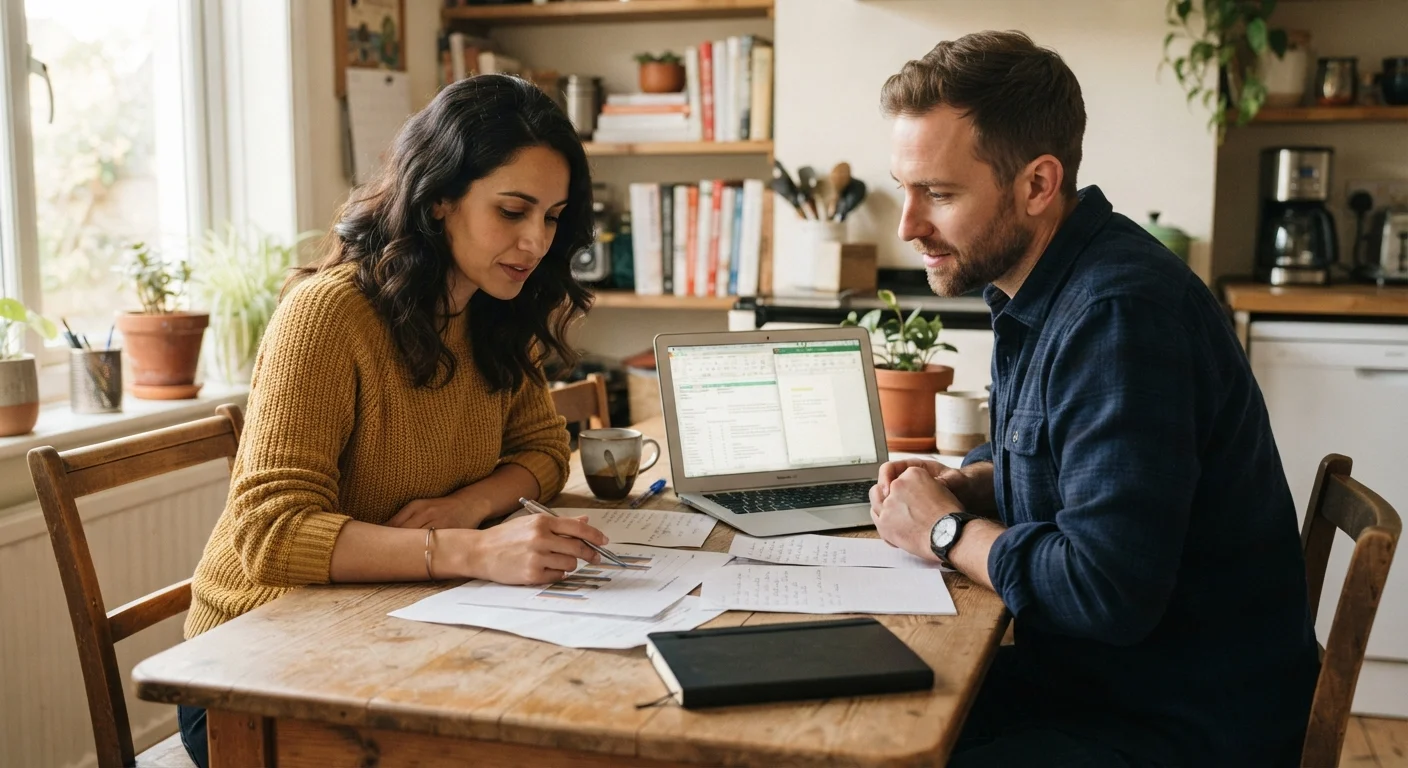
Schedule a dedicated money conversation instead of raising finances mid-argument
Financial topics raised during unrelated conflict get tangled with emotional residue from that argument. A planned conversation gives both partners time to gather thoughts, check their emotional state, and approach the topic with less defensiveness.
Name your money values before debating specific numbers
Most spending disagreements are not really about the dollar amount. They reflect different beliefs about security, freedom, generosity, or pleasure. Identifying those underlying values first gives the conversation a shared vocabulary instead of a scoreboard.
Use 'I' statements when describing how financial decisions affect you
Statements that begin with 'you always' or 'you never' read as accusations and trigger defensiveness. Describing your own experience, 'I feel anxious when our savings balance drops,' keeps the conversation about the problem rather than the person.
Agree on a personal spending threshold that each partner controls without discussion
Requiring approval for every purchase strains both autonomy and goodwill. A pre-agreed limit, such as each partner spending up to a set amount without consulting the other, removes low-stakes friction while keeping larger decisions shared.
Separate the financial problem from the person raising it
When one partner consistently earns less, carries more debt, or tends to overspend, it is easy for the other to conflate the behavior with a character flaw. Treating the financial pattern as a shared puzzle to solve, rather than evidence of personal failing, changes the dynamic. Research in couples communication consistently links this depersonalization to better conflict outcomes.
Build a shared financial framework with clear, agreed-upon goals
Without a neutral reference point, every money decision becomes a fresh negotiation. A documented framework, even a simple one listing shared savings targets and spending priorities, gives both partners something to consult that is not one person's opinion against another's.
For practical help building a shared budget structure, budgeting as a couple covers common approaches and where friction typically appears.
Quick actions to start this week
Changing how you talk about money does not require a complete overhaul of your finances. Small structural changes, like scheduling a regular check-in or agreeing on a personal spending threshold, can shift the tone of money conversations within days. These three actions require no special tools and can be done before the week is out.
For a broader set of conversation prompts to keep your relationship current, relationship check-in questions offers a practical checklist worth bookmarking.
This article is for informational purposes only and does not constitute financial or relationship therapy advice. For concerns about finances or relationship wellbeing, consider speaking with a licensed financial advisor or a qualified couples therapist.
The content on this site is for informational purposes only and is not a substitute for professional advice. Always consult a qualified professional for guidance specific to your situation.