
Leasing a Car Instead of Buying: A Balanced Look at Both Paths
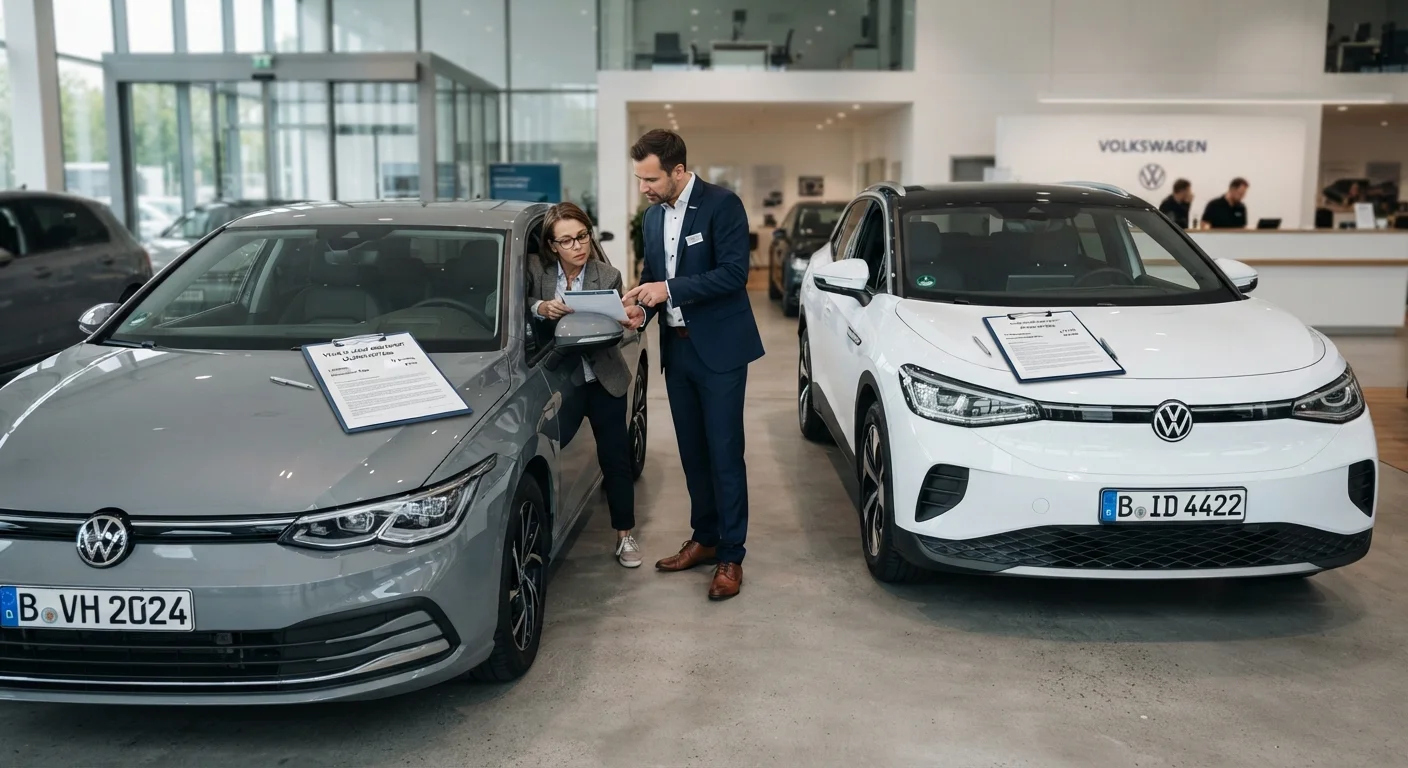
Explore the structural differences between leasing and buying, including ownership, mileage limits, long-term costs, and flexibility.
Our Verdict
Leasing makes structural sense for drivers who want lower monthly costs, prefer always having a newer vehicle, and drive predictable, moderate annual mileage. Buying makes more sense for drivers who put on high miles, want eventual ownership, or plan to keep a vehicle for many years. Neither path is universally better; the right choice depends on how you use a car and how you manage your broader finances.
Drivers who value flexibility and lower short-term costs tend to favor leasing, while those focused on long-term value and freedom from mileage restrictions tend to favor buying.
Key takeaways
- Leasing means paying for depreciation and use, not the full vehicle value.
- Buying builds equity over time; leasing does not.
- Mileage limits and wear-and-tear fees are binding lease contract terms, not suggestions.
- Monthly lease payments are typically lower than loan payments for the same vehicle.
- Long-term buyers who keep a car past loan payoff generally pay less over a decade than serial lessees.
How leasing actually works
A car lease is a contract to use a vehicle for a set period, typically two to three years, in exchange for monthly payments. Those payments cover the vehicle's projected depreciation over the lease term, plus interest (called the money factor), taxes, and fees. You do not pay for the full vehicle value.
At the end of the contract, you return the car. Some leases include a buyout option at a pre-set residual value, meaning you can purchase the vehicle if you choose. If you do not buy it, you walk away with no ownership interest.
Understanding how depreciation works is useful here because it directly determines what your lease payments will be. Vehicles that hold their value well tend to produce lower lease payments, since the depreciation amount being financed is smaller.
10K-15K
Typical annual mileage limit in a standard lease
Most manufacturer lease programs set annual allowances in this range; excess mileage fees commonly run $0.15 to $0.30 per mile over the cap.
2-3 years
Common lease contract length
The majority of consumer leases run 24 to 36 months, aligning with the period when manufacturer warranty coverage is most comprehensive.
How buying compares structurally
When you buy, whether with cash or through a loan, you own the vehicle outright once it is paid for. A financed purchase means you make payments toward the full purchase price plus interest. The mechanics of an auto loan, including how interest compounds over the loan term, affect the total you actually pay.
Ownership means no mileage restrictions, no wear-and-tear fees on return, and the ability to modify or sell the vehicle as you see fit. It also means you bear all repair costs once the warranty expires, and you assume the vehicle's depreciation as your own financial exposure.
The full cost of owning a car includes insurance, maintenance, registration, and fuel. These costs apply whether you lease or buy, so they should factor into any comparison.
Advantages and disadvantages
Each path has real trade-offs. The pros and cons below reflect structural features of leasing, not a recommendation for any particular situation.
Lower monthly payments than a comparable loan
Lease payments cover only the vehicle's depreciation during the contract term plus fees, not the full purchase price. For the same car, this typically produces a noticeably smaller monthly obligation than a standard auto loan.
Access to a new vehicle every two to three years
At lease end, you return the car and can start fresh with a newer model. Drivers who want current safety technology or updated features without the logistics of selling a used vehicle find this cycle convenient.
Warranty coverage for most of the lease term
Most new-car leases align with the manufacturer's bumper-to-bumper warranty period, so major mechanical repairs are generally covered. Out-of-pocket repair costs during the lease are often minimal compared to owning an aging vehicle.
Lower upfront costs in many cases
Many lease deals require a smaller down payment than a purchase, though putting more money down at signing reduces monthly payments. Drivers with limited upfront capital sometimes find leasing more accessible.
No equity or ownership at contract end
Every payment goes toward use of the vehicle, not toward owning it. When the lease ends, you have no asset and must either lease again, buy the car at its residual value, or find another vehicle entirely.
Mileage limits create financial risk
Standard leases allow roughly 10,000 to 15,000 miles per year. Exceeding that triggers per-mile fees, which add up quickly. Drivers with unpredictable or high annual mileage can face hundreds of dollars in overage charges at lease end.
Wear-and-tear charges at vehicle return
Lessees are responsible for returning the car in acceptable condition beyond normal wear. Dents, interior stains, or tire wear beyond contract thresholds can result in charges billed after return, sometimes unexpectedly.
Less flexibility to exit early without cost
Breaking a lease before the contract ends typically involves an early termination fee, which can be substantial. Buyers who finance can sell or trade a vehicle at any time, subject to their loan balance.
Continuous payment cycle with no payoff date
Serial lessees pay indefinitely. A buyer who finances a vehicle and pays off the loan owns it outright, eliminating that monthly cost. Over ten or more years, that difference in total outlay can be significant.
Lease terms vary by contract, not by assumption
Mileage allowances, wear-and-tear definitions, and residual values are all set in the lease agreement itself. Before signing, read the contract carefully and ask the dealer to explain any term that is unclear. Verbal assurances about flexibility are not binding.
Making the comparison work for your situation
The financial outcome depends on how long you keep a vehicle and how you use it. A driver who leases one car after another for ten years will spend more in total than one who buys a car, pays it off, and drives it for several additional years with no monthly payment. Conversely, a driver who trades in or sells every two to three years may find that leasing removes the hassle and uncertainty of the used-car market.
Mileage is the single most binding constraint in a lease. If your annual driving is above 15,000 miles or varies widely year to year, lease overage fees can erode any monthly payment savings quickly.
If you are weighing how a lease or purchase fits into a broader budget, basic budgeting principles can help you see where a monthly payment lands relative to your other obligations. And if you are comparing dealer financing to other options, focusing on the monthly payment alone can obscure the real cost of either path.
The content on this site is for informational purposes only and is not a substitute for professional advice. Always consult a qualified professional for guidance specific to your situation.