
Needs, Wants, and Savings: The Core Categories Every Budget Uses

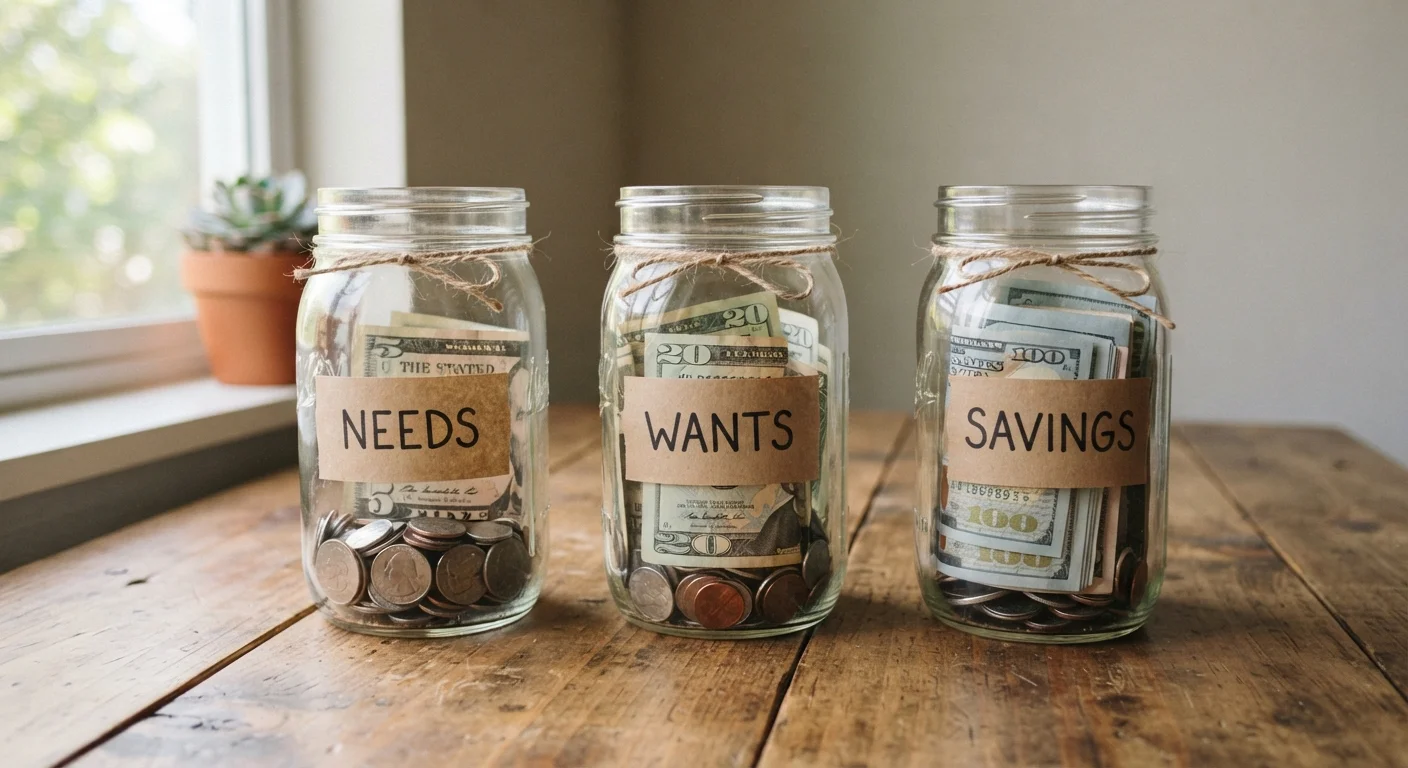
Understanding how to sort spending into categories is the first real skill in budgeting. This explainer breaks down what belongs where and why it matters.
Why categories matter before anything else
Most people who try budgeting and quit do so because they start tracking every transaction without a structure to put them in. Categories give your spending a home. Once you know which home a dollar belongs in, decisions about where to cut, where to hold steady, and where to grow become much simpler.
A budget without categories is just a list of numbers. With categories, it becomes a map you can actually read. The three categories that appear in nearly every personal budgeting system are needs, wants, and savings. Understanding what belongs in each one is the first practical skill in building a personal budget.
Need
An expense you cannot skip without immediate, material consequences such as losing housing, transportation, or health coverage. Needs are the first priority in any budget.
Want
A discretionary expense that goes beyond basic function. Wants include entertainment, dining out, and subscriptions. They are adjustable when money is tight.
Savings
Money set aside before spending on wants, directed toward goals such as an emergency fund, retirement, or paying down debt faster than the minimum required.
Discretionary spending
Spending that is flexible by nature, covering wants and optional costs. It is the category most likely to go over budget without active tracking.
Fixed expense
A cost that stays the same each month, such as rent or a car loan payment. Fixed expenses are easier to predict and typically fall under needs.
Variable expense
A cost that changes month to month, such as groceries or utilities. Variable expenses can appear in either the needs or wants category depending on what drives them.
Needs: the non-negotiable costs
A need is any expense you cannot skip without serious, near-term consequences. Housing, utilities, groceries, basic transportation, health insurance, and minimum debt payments all belong here. If not paying it means losing your home, your job, or your health coverage, it is a need.
The common mistake is padding this category. Cable TV, gym memberships, and restaurant meals feel necessary but are not. The test is simple: would skipping this payment cause immediate, material harm? If the answer is no, it belongs in wants.
Needs also include costs that vary month to month, such as your electric bill or gas for your car. Variable does not mean discretionary. For more on how fixed and variable costs interact, see the guide on fixed vs. flexible expenses.
Wants: the spending that reflects your choices
Wants cover everything you spend money on that goes beyond basic function. Streaming subscriptions, dining out, clothing beyond the basics, hobbies, travel, and entertainment all land here. These are not bad purchases. They make life workable and enjoyable. However, they are adjustable in a way that needs are not.
This category is where most budgets quietly go over. Individual want purchases tend to feel small, but they add up fast. A full look at how this works is covered in the article on discretionary spending.
When money gets tight, wants are the first category to trim. When finances are stable, wants are where you can spend without guilt, because your needs and savings are already covered.
Savings: the category that builds over time
Savings is not what is left over after you spend. In a working budget, savings is treated as a fixed category alongside needs and wants. That means you decide the amount before you allocate anything to wants.
This category covers emergency funds, retirement contributions, and any goal-based saving such as a down payment or a car purchase. Debt payments above the minimum also belong here, because they reduce what you owe and improve your financial position over time.
A useful way to measure how much you are saving relative to your income is your savings rate. The article on how to calculate your savings rate explains the formula and common benchmarks. For those ready to put saved money to work, investing essentials covers the foundational concepts.
| Number of core budget categories | 3 (needs, wants, savings) |
| Common needs share of take-home pay | Around 50% (50/30/20 guideline, widely cited in personal finance education) |
| Common wants share of take-home pay | Around 30% (50/30/20 guideline) |
| Common savings target as share of take-home pay | Around 20% (50/30/20 guideline) |
| First category to trim when money is tight | Wants |
Putting the three categories together
Once you sort your spending into needs, wants, and savings, you can see your budget as a whole. A common starting framework is the 50/30/20 guideline, which suggests spending roughly 50% of take-home pay on needs, 30% on wants, and directing 20% toward savings. The full breakdown is in the article on the 50/30/20 rule.
Those splits will not fit every household. High housing costs in some cities push needs well above 50%. Lower incomes may leave little room for any savings at first. The percentages are a reference point, not a requirement. What matters is that all three categories have a number assigned to them before the month begins.
If you share finances with a partner, the same three-category structure applies, but agreeing on what counts as a need versus a want takes an extra conversation. The guide on budgeting as a couple covers how to approach that.
This article is for general informational purposes only and is not personalized financial advice. For guidance specific to your situation, consider speaking with a licensed financial professional.
The content on this site is for informational purposes only and is not a substitute for professional advice. Always consult a qualified professional for guidance specific to your situation.