
Percentage-Based Budgeting: Pros, Cons, and When the Numbers Stop Adding Up

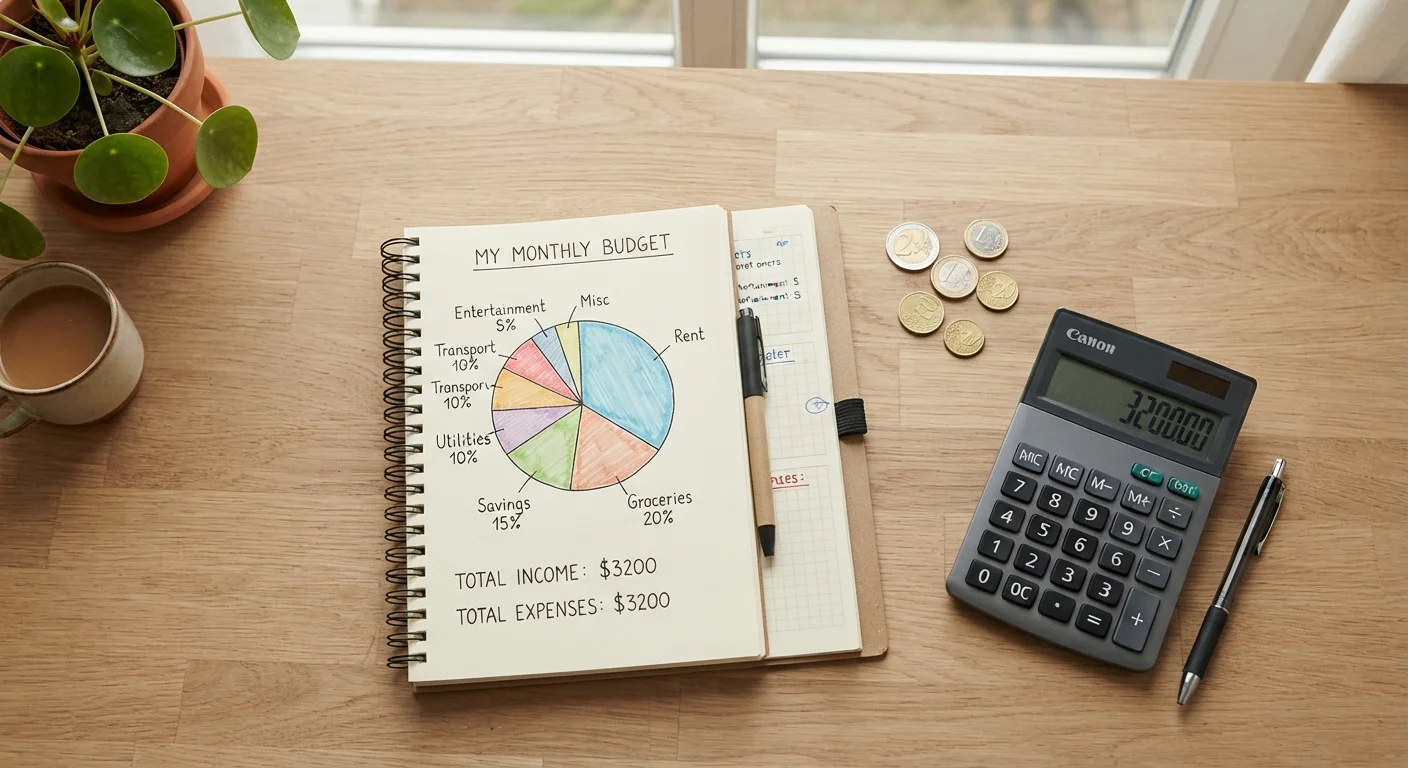
Splitting income by fixed percentages sounds clean and simple. Here is an honest look at where that approach works well and where it struggles.
Our Verdict
Percentage-based budgeting is a practical starting point for anyone who wants a simple structure without tracking every dollar. It scales with income and removes daily math. Where it struggles is with households facing high fixed costs or irregular income, where rigid percentages can create a false sense of balance while real problems go unaddressed.
People with stable, predictable income who are new to budgeting and want a clear, low-maintenance framework to build from.
Key takeaways
- Percentage-based budgeting assigns fixed portions of income to spending, saving, and other goals.
- The method works well for beginners because it scales automatically with income changes.
- Fixed percentages can fail when housing or debt costs consume a disproportionate share of income.
- No single percentage framework fits every household; adjustments are normal and expected.
- Consulting a financial professional helps tailor any budgeting approach to your specific situation.
What percentage-based budgeting actually is
Percentage-based budgeting means dividing your take-home pay into fixed proportions for different purposes. The most commonly cited version is the 50/30/20 framework: 50% toward needs (housing, utilities, groceries), 30% toward wants (dining out, subscriptions, entertainment), and 20% toward savings and debt repayment. Other splits exist, including 60/20/20 and variations designed for people with heavier debt loads.
The appeal is simplicity. Once you set the percentages, the structure adjusts automatically when your income goes up or down. You do not need to renegotiate every budget line each month. For someone just getting started, that frictionless quality matters. For a fuller picture of what budgeting can accomplish, see what a personal budget really is.
Where the approach works
Simple to set up with no complex tracking
Assigning broad percentages takes minutes and requires no specialized knowledge. Anyone with a take-home pay figure can apply the framework immediately.
Scales automatically when income changes
When earnings rise or fall, the dollar amounts in each category shift in proportion without requiring a manual budget rebuild.
Reduces daily decision fatigue
Because categories are broad, you make fewer micro-decisions about individual purchases. Spending that falls within the right bucket is pre-approved.
Builds a saving habit from day one
Earmarking a fixed percentage for savings before spending means saving is built into the structure rather than treated as whatever is left over.
The percentage model is forgiving for beginners because it does not require you to assign a dollar amount to dozens of subcategories before you start. A broad framework is easier to maintain than a granular one, and most people who attempt a detailed line-item budget abandon it within a few weeks when life does not cooperate with the plan.
Percentage budgets also adapt to income growth without a full rebuild. If your paycheck increases, your savings allocation increases proportionally without any manual adjustment. That automatic scaling is genuinely useful for people whose income grows over time or varies by season.
If you want to translate a percentage framework into a concrete monthly plan, setting up a monthly budget in seven steps walks through the process from income listing to monthly review.
Where the numbers stop working
Fixed percentages ignore high local housing costs
In expensive metro areas, rent or mortgage payments alone can exceed what the framework allocates to all needs combined, making the target unworkable without modification.
Unreliable for variable or irregular income
When monthly take-home pay swings significantly, applying a fixed percentage produces targets that shift too much to plan around, especially for savings.
Broad categories can mask overspending
Grouping many expenses under "wants" or "needs" can hide patterns. Someone might stay within the 30% wants ceiling while consistently overspending on one specific area.
Does not account for one-time large expenses
Annual costs such as car registration, insurance premiums, or medical bills do not fit neatly into a monthly percentage split and can throw the plan off without advance planning.
May underfund debt repayment in high-debt situations
A 20% savings-and-debt allocation may be mathematically too small to make meaningful progress on high-interest debt while also building an emergency fund simultaneously.
The core problem with fixed percentages is that your actual expenses do not know what percentage they are supposed to be. In many U.S. cities, rent alone can consume 40% or more of take-home pay for a median earner, leaving the 50% "needs" bucket nearly full before utilities, food, or transportation are counted. The percentage framework does not solve that problem; it just obscures it behind tidy math.
Irregular income creates a different headache. Freelancers, gig workers, and anyone with variable hours face months where the base amount shifts dramatically. Applying a fixed percentage to an unpredictable base produces a savings target that is either unrealistically high or so low it provides no traction. Envelope budgeting handles variable-income months differently and may be worth comparing.
Named percentage frameworks are not official standards
Systems like 50/30/20 originated as educational tools to simplify money management concepts. No government body or financial regulator endorses a specific percentage split as the correct one. Treat any named framework as a starting template, then adjust the numbers to reflect what your actual income and expenses require.
Couples face an added layer of complexity, since two incomes and two sets of financial habits rarely map cleanly onto a shared percentage split. Budgeting as a couple covers how shared finances introduce variables that a single percentage framework can miss.
Adjusting the percentages to fit your reality
30%+
Share of income spent on housing by many renters
The U.S. Department of Housing and Urban Development defines households spending more than 30% of income on housing as cost-burdened, a threshold many urban renters exceed.
~40%
Americans without enough savings for a $400 emergency
Federal Reserve survey data has consistently shown that a large share of U.S. adults would struggle to cover an unexpected $400 expense without borrowing or selling something.
No budgeting framework is a rule. The percentages in any named system are starting points, not targets handed down from a regulatory body. If your housing costs are genuinely high and unavoidable right now, shifting the needs allocation to 60% and trimming wants to 20% is a reasonable response, not a failure.
The same logic applies to debt. Someone carrying high-interest debt may want to push the savings-and-debt portion to 25% or 30% temporarily. Practical approaches to growing savings and paying down debt cover how those two goals interact and which to prioritize first.
The tool you use to track the percentages matters less than consistency. Paper, spreadsheet, or app approaches each work; the difference is which method you will actually maintain. Pick the one that fits your habits rather than the one that sounds most rigorous.
This article is for general informational purposes only and does not constitute personalized financial advice. For guidance specific to your situation, consult a qualified financial professional.
The content on this site is for informational purposes only and is not a substitute for professional advice. Always consult a qualified professional for guidance specific to your situation.